Bringing digital assets further into the financial mainstream will require payment providers, insurers, brokers and regulators to understand how their respective roles fit together – rather than developing solutions in isolation.
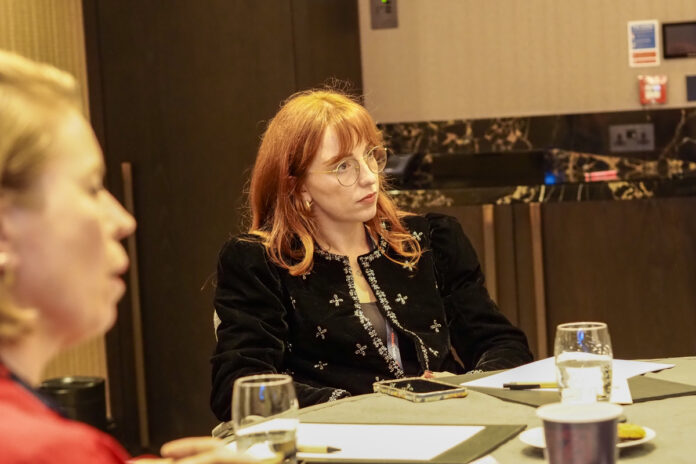
That was one of the clearest conclusions from a roundtable at the 2026 Capital Pioneer Digital Assets Summit involving representatives from RTGS Global, Native and Howden.
Moderated by Liz Pfeuti, marketing director at Rhotic Media, the roundtable brought together Jane Mercer, head of product and client solutions, and Folayan Odunaiya, director of partnerships and client solutions, at RTGS Global; Alex Saleh, head of partnerships at specialist digital-assets insurance broker Native; and Josh Patching, senior account executive, and Charlie Dingwall, account handler at global insurance broker Howden.
Together, they discussed the role of insurance, regulation, payments infrastructure and collaboration in supporting the next phase of digital-asset adoption.
Although the participants approached digital assets from different parts of the financial system, the discussion revealed a shared challenge: technological innovation is moving quickly, but adoption depends on institutions being able to understand, manage and protect against the risks that come with it.
The discussion also highlighted how insurance fits into the institutional adoption process for new payment infrastructure.
RTGS Global is focused on improving the movement of money across borders, including through infrastructure capable of connecting fiat and digital assets. Mercer said some of the clearest use cases for stablecoins are in markets where traditional cross-border payments remain slow or inefficient.
In these cases, customers may not necessarily want to hold stablecoins themselves, but they may recognise the value of being able to move money more quickly between currencies and jurisdictions.
But conversations with institutional clients frequently go much further than questions of efficiency.
“I think today is probably the first day I’m really understanding how insurance comes into play,” Odunaiya said, referring to the way conversations with institutional clients can move from potential savings and efficiencies to questions around compliance, protection and security.
He explained that while one stakeholder might immediately understand the potential savings offered by new payment infrastructure, compliance and risk teams may ask very different questions around protection, security and responsibility.
That highlighted a potentially important lesson for payments providers: that simply demonstrating what new technology can achieve may not be enough. Institutions also need to understand what sort of protections they have when they use it.
For Odunaiya, the discussion also demonstrated the value of bringing expertise from different parts of financial services together. “I think there’s a lot to learn from your industry,” he told the insurance participants.
Paying attention to evolving risks
The learning ran in both directions.
For insurers and brokers, the challenge is that digital-asset risks can evolve faster than established underwriting models can adapt.
The insurance participants described an environment in which underwriters may need to examine the protections a business has put in place rather than relying solely on long histories of claims data.
Digital-asset businesses can introduce new cybersecurity, custody and operational risks, while technologies and business models can evolve before insurers have accumulated enough loss experience to model them conventionally.
This places greater emphasis on understanding how firms protect assets, respond to breaches and mitigate losses before they happen.
Similarly, Patching and Dingwall at Howden emphasised the importance of education, with Dingwall describing the broker’s role in translating a technically complex sector into terms insurers can understand.
“The most important thing about digital assets is the education piece and people trusting it,” Dingwall said.
Insurers ultimately need to understand the risks behind a digital-asset company before putting capital behind the business, which is why education is becoming an integral part of the broker’s role.
There are signs that this understanding is developing. Patching described a considerable expansion in the insurance market available to digital-asset businesses compared with several years ago, with significantly more insurers now willing to consider a wider range of risks.
“Today, I’ve got 60 to 70 markets I could speak to for a variety of different risks,” Patching said.
Collaboration can accelerate the learning curve
Perhaps one of the more unusual features of the discussion was the extent of collaboration that takes place even between nominal competitors.
The competitive nature of the market was evident from the outset, with Saleh describing it as offering “lots of opportunity and lots of competition”.
The insurance participants described a relatively small specialist market in which brokers often encounter similar questions from insurers and clients. Knowledge generated through new use cases can therefore spread through conversations across the market, improving understanding of emerging risks.
One participant estimated that there may be only around 15 people in London capable of placing some of these specialist digital-asset risks effectively, illustrating both the depth of expertise required and the relatively close-knit nature of this market.
Participants argued that this matters because poor risk placement does not only affect one broker or client. If coverage fails to respond as expected when a claim occurs, confidence in the wider market can also be damaged.
Conversely, better understanding can help insurers become more comfortable with risks, potentially improving both capacity and pricing over time.
The discussion suggested that expertise accumulated in highly specialised areas of digital assets can eventually filter into the wider insurance market.
Different priorities, common destination
The roundtable did not reveal major disagreement so much as different starting points.
RTGS Global sees the opportunity through the practical friction involved in moving money. Insurance specialists naturally focus more heavily on what happens when transactions, systems or controls fail.
In practice, those two perspectives quickly meet. Moving money faster is only useful to an institution if its compliance, risk and insurance teams are comfortable with what happens when something goes wrong.
The same pattern was evident around regulation.
Participants broadly agreed that clearer regulation could support rather than suppress adoption. Institutions may be reluctant to take on risks when the rules remain uncertain, while clearer frameworks can help compliance teams understand what they are permitted to do.
Odunaiya said compliance was already a practical consideration in conversations with institutions operating across markets. “How do we do this in a way that is compliant?” he said, describing one of the questions clients are asking as they consider new payment infrastructure.
At the same time, fragmented regulatory regimes remain a constraint.
The technology may make global movement of value possible, but operating legally and compliantly across multiple jurisdictions is considerably more complicated.
That gap between what technology makes possible and what institutions can confidently implement may ultimately be where greater collaboration delivers the most value.
Payment providers need to understand insurance, compliance and risk. Insurers need to understand the technology and emerging use cases they are being asked to protect. Regulators need visibility into how those models work in practice.
What the discussion made clear is that the next stage of digital-asset adoption will not be solved by faster infrastructure alone. Payment providers need insurers to understand the risks associated with what they are building, while insurers need payments and digital-asset specialists to explain how those risks are changing.
The more quickly that knowledge moves between them, the easier it becomes to turn new technology into something institutions can actually use and benefit from.